

- Bitcoin does not have one permanent relationship with other assets
- What correlation measures—and what it does not
- Regimes change which forces matter most
- Shared liquidity can create shared price moves
- Bitcoin has its own market structure and risks
- Why a past correlation is not a stable hedge
- A practical way to assess claims about co-movement
- Risk reminder
- Bitcoin does not have one permanent relationship with other assets
- What correlation measures—and what it does not
- Regimes change which forces matter most
- Shared liquidity can create shared price moves
- Bitcoin has its own market structure and risks
- Why a past correlation is not a stable hedge
- A practical way to assess claims about co-movement
- Risk reminder
Why Bitcoin’s Relationship With Other Assets Changes Over Time


Bitcoin does not have one permanent relationship with other assets
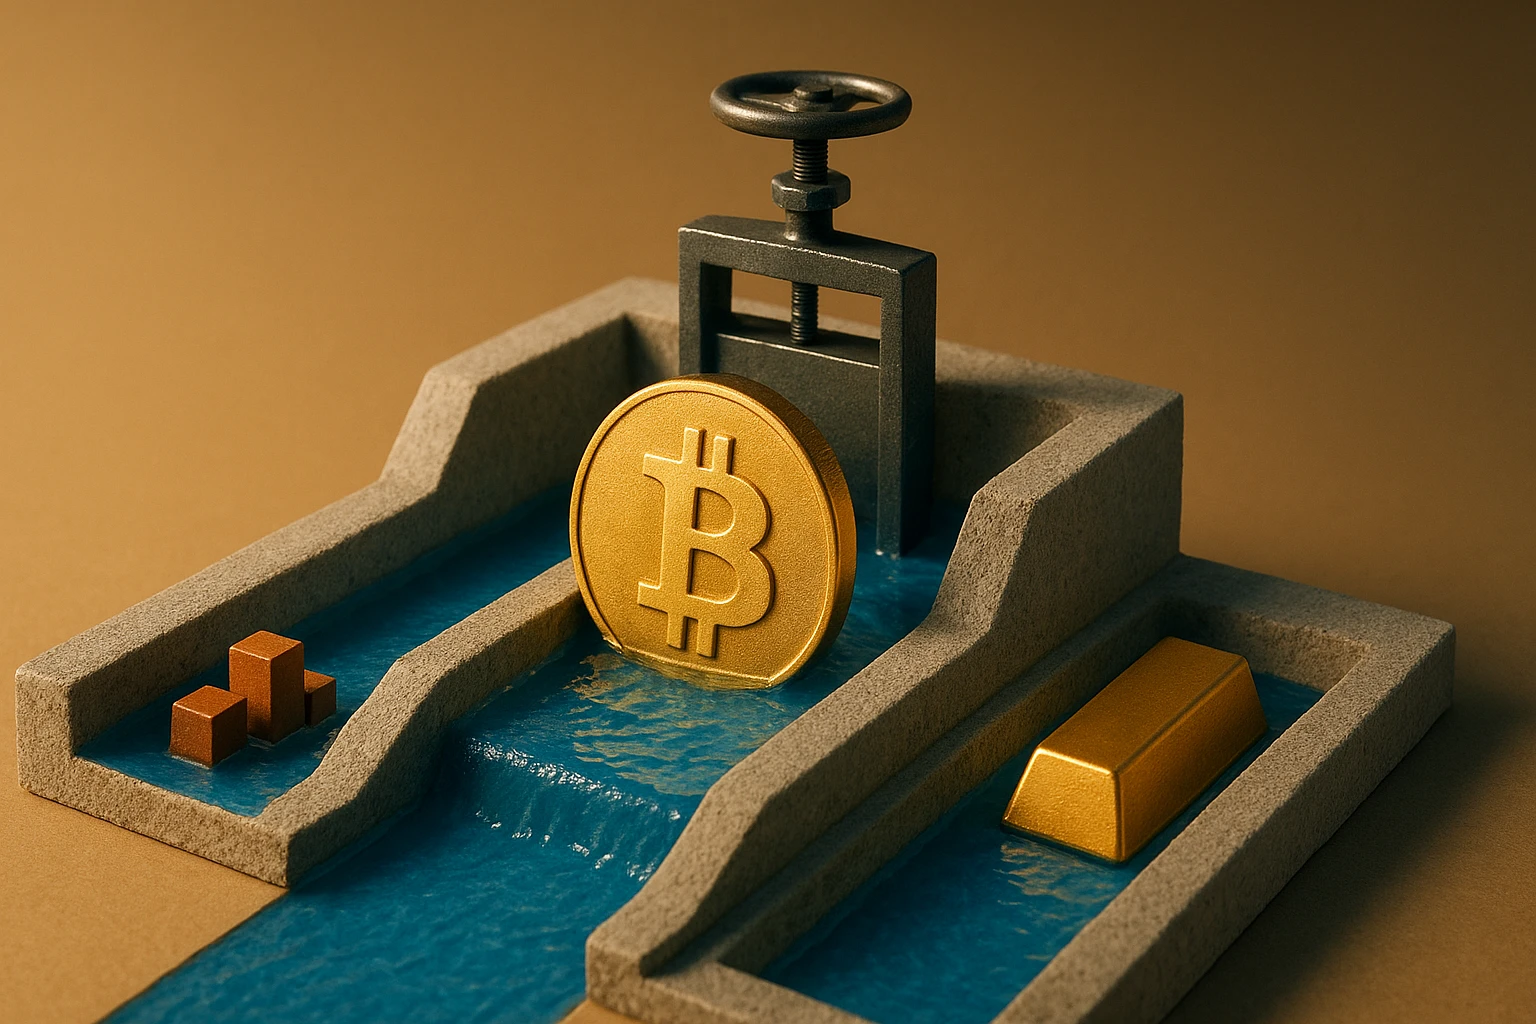
Bitcoin is sometimes described as an alternative to stocks, gold, bonds or cash. That description can suggest that it will consistently move differently from those assets, or offer protection when they fall. Neither outcome is guaranteed. Bitcoin’s relationship with other markets changes as the forces influencing investors change.
In one period, investors may trade Bitcoin and growth-oriented shares in a similar way because both are sensitive to expectations about economic growth and the availability of money. In another, a Bitcoin-specific event may dominate its price, weakening that connection. A sudden need for cash can also push investors to sell assets that have little in common. These are different mechanisms, and they can produce similar price movements for a time.
Understanding this variability matters because a past correlation is a description of a particular sample of returns, not a dependable promise about what will happen during the next market shock. Bitcoin may diversify a portfolio in some periods and provide little diversification in others. It should not be treated as a stable hedge simply because it once moved differently from another asset.
What correlation measures—and what it does not
Correlation summarizes how two sets of returns moved in relation to each other over a chosen period. A positive correlation means they tended to rise and fall together in that sample. A negative correlation means they tended to move in opposite directions. A value near zero means there was no consistent linear relationship in the observations used.
Correlation does not explain why assets moved together, prove that one caused the other, or guarantee the same relationship in the future. It also does not show the size of gains or losses. Two assets can have a strong positive correlation while one moves much more sharply than the other. And a low average correlation can hide stretches when both fall at the same time.
The answer depends on how returns are measured. Daily, weekly and monthly data can give different results; so can a short rolling window and a long historical sample. Bitcoin trades continuously, including weekends, while many traditional markets follow set trading hours. Comparing a weekend Bitcoin move with a stock market that is closed can complicate timing. The chosen currency, price source and start and end dates also affect the comparison.
Regimes change which forces matter most
A market regime is a period in which certain economic or market forces have more influence than others. It is not always possible to identify a regime clearly while it is unfolding. Still, the idea helps explain why Bitcoin’s relationship with stocks, bonds, gold or currencies can shift.
Growth and risk appetite
When investors are optimistic about growth, they may be more willing to hold assets they see as risky or sensitive to future opportunity. When concern rises, they may reduce exposure to several such assets at once. Bitcoin can then move in the same broad direction as shares, particularly when market participants are focused on risk appetite rather than on Bitcoin’s distinct properties.
This is not a fixed classification of Bitcoin. Investors can disagree about whether it behaves like a technology-related risk asset, a monetary alternative or something else. The dominant interpretation can change with market conditions and the reasons people are buying or selling.
Interest rates, inflation and policy expectations
Changes in expectations about interest rates and inflation can affect assets through different channels. Higher expected returns on some traditional instruments may make investors reassess the appeal of assets that do not pay interest. At the same time, inflation concerns can increase interest in assets that some people view as alternatives to conventional money. Those forces can point in different directions, so the label “inflation hedge” alone does not determine Bitcoin’s response.
What matters is the surprise and the market’s interpretation, not just the headline. An inflation report, for example, may alter expectations about policy, growth or future liquidity. Those revised expectations can affect Bitcoin and other assets together even if their long-term investment cases differ.
Stress and the demand for cash
During market stress, investors may sell assets to meet obligations, reduce borrowed exposure or raise cash. Selling can affect assets that are not economically alike. If many participants need liquidity at once, the immediate need to sell may outweigh the reasons they hold a particular asset. This can make a supposed diversifier fall alongside the assets it was meant to diversify.
Later, the same asset may recover for reasons specific to its own market. A short period of co-movement during a liquidity shock does not establish a permanent relationship, just as a period of divergence does not prove reliable protection.
Shared liquidity can create shared price moves
Liquidity refers to how easily an asset can be bought or sold without causing a large change in price. It includes the availability of willing buyers and sellers, the depth of trading, and access to funding. Liquidity conditions can influence both traditional markets and crypto markets, though not in identical ways.
When funding is easy and investors are willing to take risk, demand may support a range of assets. When funding becomes harder to obtain or investors reduce risk, selling pressure can spread across markets. Investors may also use the same broad strategies across different assets, such as reducing positions when volatility rises. Those shared decisions can increase correlation, even if there is no direct link between the assets’ underlying uses.
Liquidity can also be uneven. Bitcoin trades around the clock, but trading depth varies by venue and time. A large order in a thinner market can move its price more than a similar order in a deeper market. During fast markets, quoted prices may change quickly and the cost of executing a trade may rise. These conditions can make short-term co-movement look different from what a longer sample suggests.
Bitcoin has its own market structure and risks
Bitcoin’s price can respond to factors that do not directly drive shares or bonds: changes in crypto-market demand, exchange access, network-related news, investor expectations about adoption, and shifts in the way Bitcoin is used or held. These forces can temporarily outweigh broad economic conditions and cause Bitcoin to diverge from other assets.
It is useful to distinguish the asset from the ways people gain exposure to it. Holding spot Bitcoin means owning the asset, but a holder may use a custodian or an exchange, each of which introduces operational and counterparty considerations. Self-custody avoids reliance on a custodian for access but makes the holder responsible for securing keys and recovery information. A failure to access an account or a loss of keys is different from a change in Bitcoin’s market relationship with stocks.
Derivatives, such as futures or perpetual contracts, provide price exposure without being the same as owning spot Bitcoin. Leverage, margin requirements, funding payments and forced liquidations can affect trading behavior. If prices move sharply, liquidations may add to selling or buying pressure. Derivative-market activity can therefore amplify a move, but it does not mean all spot holders face the same mechanics.
DeFi introduces another set of connections. Bitcoin-related exposure may be represented through wrapped or tokenized assets, or used in lending and collateral arrangements. These systems can depend on smart contracts, bridges, stablecoins and liquidity pools. If collateral values fall, automated liquidations can create further selling; if a token, bridge or stablecoin fails, the resulting loss may be specific to that arrangement. Such risks can interact with wider market stress without being identical to Bitcoin’s own network or spot-market risks.
Why a past correlation is not a stable hedge
A hedge is intended to offset a particular risk. To evaluate whether an asset serves that purpose, it is not enough to find a period when it moved in the opposite direction from another asset. The relevant question is how it behaves during the specific conditions the holder wants to manage, including the scale and timing of losses, the cost of holding the position and the possibility that the relationship changes.
Bitcoin has not shown a guaranteed, consistent inverse relationship with stocks, bonds or any other broad asset group. It may rise while another asset falls in one episode and fall alongside it in another. Even a negative correlation over a long sample can be misleading if it results from a few unusual periods or disappears during the moments when protection is most needed.
Diversification and hedging are also not identical. Diversification spreads exposure across assets that may behave differently, which can reduce reliance on a single source of risk. A hedge is more specifically intended to offset a defined exposure. Neither approach removes the possibility of loss, and a low historical correlation does not by itself establish that an asset is suitable for either role.
A practical way to assess claims about co-movement
When you encounter a claim that Bitcoin is “correlated with” or “uncorrelated to” another asset, consider the following questions before drawing a conclusion:
- What period is being measured? Ask whether the claim uses a short episode, a rolling window or a longer sample, and whether the chosen period includes unusual market conditions.
- What returns are compared? Check the frequency, currency, price source and time alignment. Different choices can produce different results.
- Is the claim about average behavior or stress behavior? A relationship across ordinary periods may not describe what happens when investors rush to raise cash.
- Which Bitcoin exposure is involved? Spot ownership, an exchange-traded product, a leveraged derivative and a DeFi position can carry different operational and market risks.
- What mechanism could connect the assets? Shared risk appetite, funding conditions or forced selling offer possible explanations, but correlation alone cannot confirm them.
- Does the claim confuse diversification with protection? An asset that sometimes moves independently may still fall sharply when protection is most wanted.
These questions do not make future price relationships predictable. They help separate a measured historical pattern from a broader claim about what Bitcoin will do. A useful explanation should describe the sample, the possible mechanism and the limitations, rather than presenting correlation as a permanent property of an asset.
Risk reminder
Bitcoin and crypto-related products can be highly volatile and can involve market, liquidity, custody, counterparty, technology and leverage risks. You may lose some or all of the value committed, and past relationships between assets do not ensure future diversification or protection. This article is general education, not personalized financial advice.